Mexico Extends the Electronic Value Declaration Deadline: Key Dates and Compliance Considerations for Importers
Mexico has granted importers additional time to prepare for the mandatory electronic submission of the Manifestación de Valor Electrónica (MVE), or Electronic Value Declaration. According to the announcement issued by Mexico’s tax and customs authorities in October 2026, the deadline has been extended to October 31, 2026, while mandatory implementation will begin gradually on November 1, 2026, depending on the applicable customs regime.
This phased approach gives companies additional time to adapt their internal procedures, organize supporting documentation, and coordinate with customs brokers and other stakeholders involved in import operations.
What Is the Electronic Value Declaration?
The MVE is an electronic declaration submitted through Mexico’s Single Window for Foreign Trade Procedures (Ventanilla Única de Trámites de Comercio Exterior). It allows importers to report the information used to determine the customs value of imported goods and provide the supporting documentation required under Mexican customs regulations.
The electronic process replaces the traditional paper-based approach with a digital submission system. Consequently, companies must ensure that the information declared is accurate, complete, and consistent with their commercial and customs records.
Gradual Implementation Schedule
Under the announced transition schedule, the mandatory submission dates vary according to the customs regime involved.
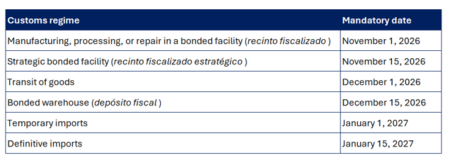
Companies should identify the customs regimes applicable to their operations and confirm the corresponding implementation date before establishing their compliance timelines.
Source: Holland & Knight, “Mexico Further Extends Deadline for the Electronic Value Declaration,” October 7, 2026.
Documentation and Recordkeeping Requirements
Preparing the MVE involves more than completing an electronic form. Importers must have access to the commercial, financial, contractual, and logistics information needed to support the declared customs value.
Depending on the transaction, relevant documentation may include:
- Commercial invoices and purchase orders.
- Transportation and insurance documents.
- Proof of payment.
- Contracts associated with the transaction.
- Information regarding the origin and provenance of the goods.
- Documentation supporting additions to the transaction price, known as conceptos incrementables.
Maintaining an organized electronic file can help companies verify the accuracy of the information submitted and respond more efficiently to potential requests from customs authorities.
Transitional Facilitation Measures
During the transition, certain administrative facilities may reduce the need to upload the same information more than once.
For example, some supporting documents may not require a separate transmission when they are already attached to the corresponding customs declaration (pedimento). In addition, companies may use Form E15 to report general information about contracts associated with the MVE, rather than uploading each complete contract individually through the Single Window, subject to the applicable requirements.
These facilities do not eliminate the obligation to maintain supporting records. Companies should preserve the relevant contracts and documentation in their electronic foreign trade files and make them available to the authorities when required.
How Companies Should Prepare
Importers can use the additional preparation period to review their processes and address potential compliance gaps before the applicable mandatory date.
- Map customs operations. Identify the customs regimes used by the company and determine which implementation date applies to each type of import.
- Review supporting documentation. Verify that invoices, payment records, contracts, freight charges, insurance costs, and other relevant documents are available and consistent.
- Coordinate with customs brokers and suppliers. Establish clear procedures for obtaining missing information and resolving discrepancies before an import declaration is processed.
- Strengthen digital recordkeeping. Organize documents in a structured electronic file to facilitate retrieval, verification, and compliance reviews.
- Establish internal controls. Assign responsibility for preparing, reviewing, transmitting, and retaining MVE information, including procedures for correcting inconsistencies.
Why Early Preparation Matters
Although the extension provides additional time, it does not eliminate the underlying compliance obligations. Incomplete documentation, inconsistent transaction information, or errors in the declared customs value may expose importers to customs reviews and potential penalties, depending on the circumstances and applicable regulations.
For companies with frequent imports or complex supply chains, early preparation can also help reduce administrative bottlenecks and improve coordination between finance, purchasing, logistics, and foreign trade teams.
Mexico’s phased implementation of the Electronic Value Declaration represents an important change in customs documentation and compliance procedures. Businesses should take advantage of the additional preparation period to verify their documentation, review internal controls, and establish reliable processes for meeting the applicable deadlines.
A proactive approach can help importers navigate the transition more efficiently while maintaining accurate records and supporting compliance with Mexico’s foreign trade requirements.
At Mexcentrix, we help companies navigate Mexico’s foreign trade and regulatory environment. Contact our team to learn how we can support your operations and compliance strategy.